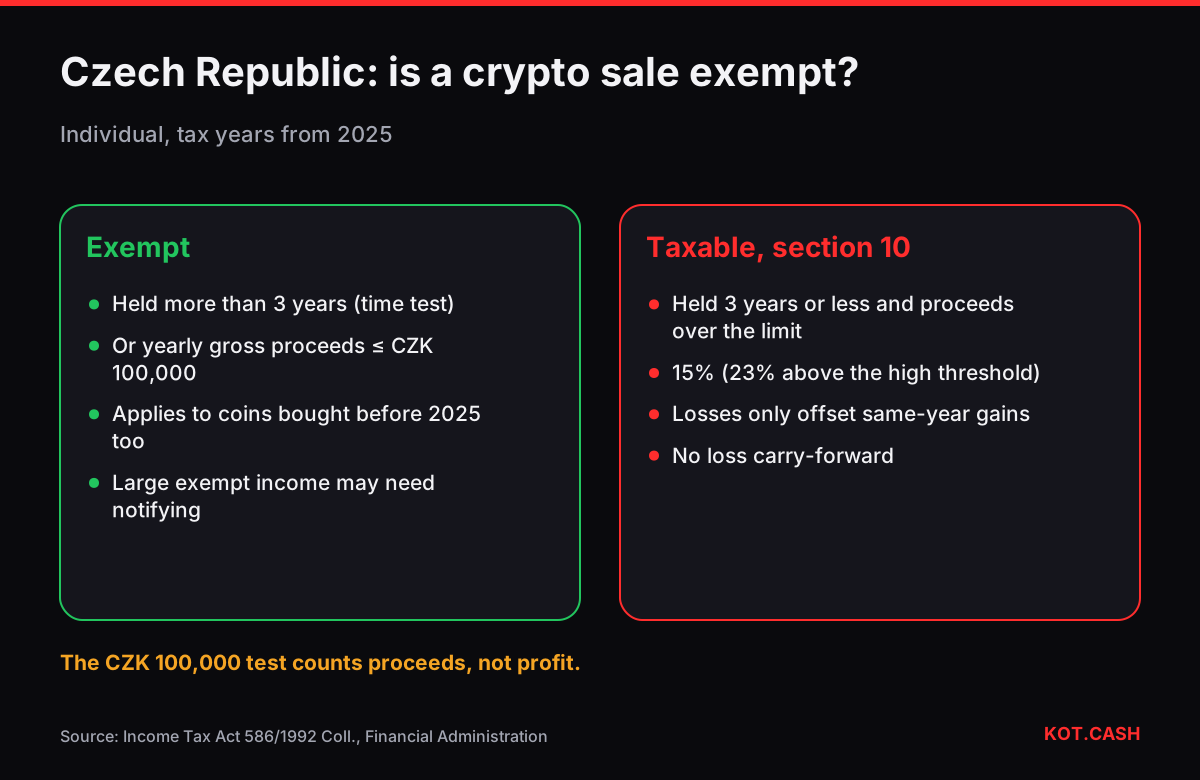
Since the 2025 tax year, Czech law exempts an individual's income from selling crypto-assets in two situations: when the coins were held for more than three years (the time test), or when your total gross income from such sales in the year does not exceed CZK 100,000. Outside those exemptions, the gain is other income under section 10 of the Income Tax Act, taxed at 15%, or 23% on the part of your income above the higher-rate threshold. Before 2025 there was no holding period exemption for crypto at all.
The two exemptions compared
The amendment that introduced the rules took effect on 1 January 2025 and applies to crypto-assets acquired before that date as well, as long as the holding period is met.
- Time test, three years. Income from the sale is exempt if more than three years pass between acquisition and sale. The test is per unit, so FIFO or another consistent identification of lots matters.
- Small amounts, CZK 100,000. If the total gross income (proceeds, not profit) from selling crypto in a calendar year is CZK 100,000 or less, it is exempt. Above that amount, the income is taxed in full, not just the excess.
The second rule counts proceeds. Selling CZK 120,000 worth of coins with a profit of only CZK 5,000 is above the limit, so that CZK 5,000 is taxable unless the coins pass the three-year test. The holding period calculator marks when each lot passes three years.
How taxable gains are calculated
Taxable income is the proceeds minus the documented acquisition price of the coins sold and related expenses. Under section 10, a loss on one sale can be offset against gains of the same kind in the same year, but an overall loss from section 10 income cannot reduce your salary or be carried forward. Timing sales within one calendar year therefore matters.
| Sale | Proceeds | Held | Result |
|---|---|---|---|
| BTC bought 2021 | CZK 200,000 | 4 years | exempt, time test |
| ETH bought 2024 | CZK 60,000 | 8 months | gain CZK 15,000 |
| SOL bought 2024 | CZK 50,000 | 6 months | loss CZK 10,000 |
Proceeds from the ETH and SOL sales total CZK 110,000, above the CZK 100,000 limit, so the small-amount exemption does not apply to them. Their net result is a gain of CZK 5,000, taxed at 15%: CZK 750. The BTC sale is exempt under the time test and does not count, which is how most advisers read the interaction of the two exemptions; check the Financial Administration's guidance for your case.
If you buy the same coin in many small purchases, record which lots each sale draws from. Mixing lots carelessly can turn a sale that would have passed the three-year test into a taxable one on paper.
Swaps and payments
The Czech rules talk about income from the sale or other disposal of crypto-assets. Paying for goods with crypto is a disposal. How a crypto-to-crypto swap is treated has been debated; the Financial Administration's guidance treats barter as income in kind, which would make a swap taxable unless an exemption applies. Because of that uncertainty, keep full records of every swap, including the CZK value of both sides. The swap taxation comparison shows how other countries handle it.
Rates and filing
Personal income tax is 15% on income up to the threshold of 36 times the average wage and 23% above it. Section 10 income is added to your other taxable income in the annual return. The deadline for a paper return is normally 1 April, and later for electronic filing or when a tax adviser files for you. Crypto mining or trading as a business is taxed under section 7 as self-employment income with social and health insurance contributions.
Large exempt income
Exempt income is not always invisible. Czech law requires individuals to notify the tax office of certain exempt income above a high threshold; the Financial Administration publishes the current rules. If you plan a large sale of coins held for more than three years, check whether you need to report it even though no tax is due.
Records
- Acquisition date, price and fees of every lot, needed for the three-year test.
- Yearly totals of gross proceeds, needed for the CZK 100,000 test.
- For non-custodial swaps such as on KOT.CASH, order links with amounts and hashes.
- CZK values from a consistent source, such as the Czech National Bank rate for the fiat leg.
FAQ
Is crypto tax-free after three years in the Czech Republic?
Yes, from the 2025 tax year: income from selling crypto-assets held more than three years is exempt.
What is the CZK 100,000 crypto exemption?
If your total gross proceeds from crypto sales in a year are CZK 100,000 or less, the income is exempt. Above it, all is taxable unless the time test applies.
What is the Czech crypto tax rate?
Taxable crypto income is taxed at 15%, or 23% on income above 36 times the average wage.
Can crypto losses reduce my salary tax?
No. Losses within section 10 income can only offset gains of the same kind in the same year and cannot be carried forward.
Does the three-year rule apply to coins bought before 2025?
Yes. The time test applies to sales from 2025, including coins acquired earlier.